Stock turnover says how often your stock turns over completely in a year. The formula: annual cost of goods sold divided by average stock, both at cost. If it comes out at 3, you have sold your stock three times and rebuilt it three times - on average every item then sits in the shop for about four months.
The maths
€120,000 cost of goods a year, €40,000 average stock. 120,000 ÷ 40,000 = 3.0. Days in stock is the inverse: 365 ÷ 3 = roughly 122 days.
The most honest average stock comes from several counting dates - opening and closing balance alone distort things when the Christmas assortment is on the shelf in December. Four quarterly figures are quite enough.
- 3.0
- stock turns a year
- 122 days
- average days in stock
- 4
- counting dates for the average
€120,000 cost of goods, €40,000 stock
365 divided by the turn
one per quarter - two figures distort too much
What counts as a good figure
There is none that holds across sectors. A grocer turns in double digits, a furniture store sits below two, and both are right. Compare your turn to an industry figure off the internet and you are usually comparing two different methods.
The useful comparison is your own: the same shop, the same quarter last year, the same formula. And the second useful comparison is inside the shop - which category turns, which stands.
Why the figure looks low in small shops
Usually not because of bad buying. Rather because choice on a small floor inevitably costs depth: show twelve categories with little room and you carry a few units of each - and few units per item mean small order quantities, worse terms, and rarely the point at which something really turns.
A low turn is therefore often a symptom of liquidity, not of buying quality. What sits behind it is set out in tied-up capital in retail - and what a single misjudgement really costs, in what a bad buy really costs.
The special case: goods that are not yours
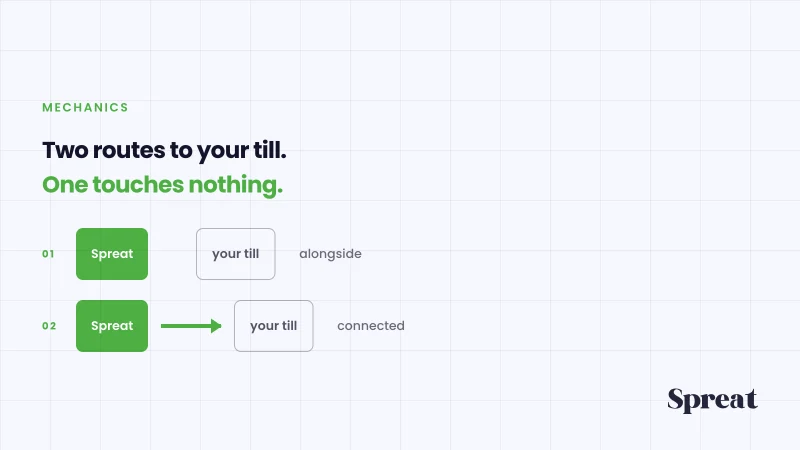
If the floor carries goods that belong to the brand until they sell, they do not appear in your stock at all. Your turn improves - not because you buy better, but because the denominator gets smaller.
That is not creative accounting as long as you know it: the metric then measures only your own assortment, while the floor shows more than before. Anyone wanting to steer both keeps two numbers - turnover for your own goods, sales per metre for the floor.
Annual cost of goods sold divided by average stock, both at cost. For the average, take several counting dates, not just the opening and closing balance.
The same information the other way round. Days in stock is 365 divided by the turn. A turn of 3 is about 122 days, a turn of 6 about 61.
At cost, in both numerator and denominator. Divide turnover by stock at cost and you get a bigger number that means nothing - that is exactly how industry figures that do not match one another come about.
Economically no, because it is not your capital. It stands on your floor and has to be steered there, but it does not belong in the turnover calculation of your own stock.